Mortgage Offset Accounts: Are You Using Yours Correctly?
An offset account can save you thousands in interest, but most borrowers miss simple ways to maximise it. Here's how to use yours properly.

What an Offset Account Actually Does
An offset account is an everyday transaction account linked to your home loan. The balance sitting in it is subtracted from your loan principal before interest is calculated each day.
So if you owe $550,000 and have $30,000 in your offset, you're only charged interest on $520,000. At a rate of 6.2% p.a., that one move saves you roughly $1,860 in interest over a year — without making a single extra repayment.
The maths is simple, but the habits around it are where most borrowers fall short.
The Most Common Mistakes Borrowers Make
1. Leaving your salary in a separate savings account If your pay goes into a high-interest savings account earning 4.5% (taxed), while your mortgage charges 6.2%, you're going backwards after tax. Park your salary directly into the offset instead.
2. Only keeping a small buffer in there Some borrowers treat the offset like a petty cash tin — $2,000 in, $1,800 out every fortnight. The higher your average daily balance, the more interest you save. Let it build.
3. Not knowing if your loan is actually offset-eligible Many basic or "no-frills" variable loans don't come with an offset. Fixed-rate loans in Australia typically don't offer a true 100% offset either — some lenders offer a partial offset or a redraw facility instead, which is not the same thing. Check your loan documents or call your lender.
4. Paying annual fees that outweigh the savings Offset accounts often sit on package loans that charge $395–$750 per year in fees. If your average offset balance is only $5,000–$10,000, the fee may cancel out most of the benefit. Run the numbers before assuming it's worth it.
5. Confusing redraw with offset Redraw lets you access extra repayments you've already made. Offset keeps your money genuinely separate from the loan. For tax purposes — particularly if you later convert your home to an investment property — this distinction matters significantly. Speak to your accountant if that scenario applies to you.
Ready to get started? Post your job free and local home loans tradies can quote.
How to Maximise Your Offset Balance Day-to-Day
These practical habits can meaningfully lift your average daily balance:
- Direct all income here first. Salary, freelance payments, rental income, tax refunds — everything lands in the offset before it goes anywhere else.
- Use a credit card for daily spending (paid in full each month). Your offset balance stays higher for the entire billing cycle while the credit card floats your expenses. This only works if you clear the card fully each month — carrying a balance defeats the purpose entirely.
- Delay discretionary transfers. If you're moving money to a managed fund or making a lump-sum payment elsewhere, do it at the end of the month rather than day one.
- Pool accounts where your lender allows it. Some lenders let you link multiple offset accounts to the one loan — useful for couples who want to keep spending accounts separate but still offset together.
Partial vs 100% Offset: What's the Difference?
| Feature | 100% Offset | Partial Offset |
|---|---|---|
| How much offsets the loan | Full balance | A set percentage (e.g. 40%) |
| Interest savings | Maximum | Reduced |
| Common on | Variable loans | Some older or basic loans |
| Flexibility | High | Low |
If you're on a partial offset, it's worth asking your lender whether upgrading to a 100% offset package makes financial sense, especially as your balance grows.
When an Offset Account Is Less Useful
An offset becomes less powerful when:
- Your loan balance is very low (under $100,000) and the fee exceeds the interest saving
- You're on a fixed rate with no offset feature and are being charged for a package you don't use
- You're consistently spending your offset balance down to near zero
In those cases, making additional repayments directly into a redraw-enabled loan may produce a similar or better outcome without the account fee.
Actionable Takeaway
This week, check two things: the average balance sitting in your offset over the past three months, and what you're paying annually in loan package fees. If your average balance isn't at least covering the fee in equivalent interest savings — or if your salary is landing somewhere other than the offset — you're leaving money on the table. Small changes to where your pay lands and how you time your spending can quietly cut months off your mortgage over a 25–30 year term.
Done researching? The next step is getting real quotes.
Get My Quotes — It’s Free →No obligation. Takes 60 seconds.
Business for sale
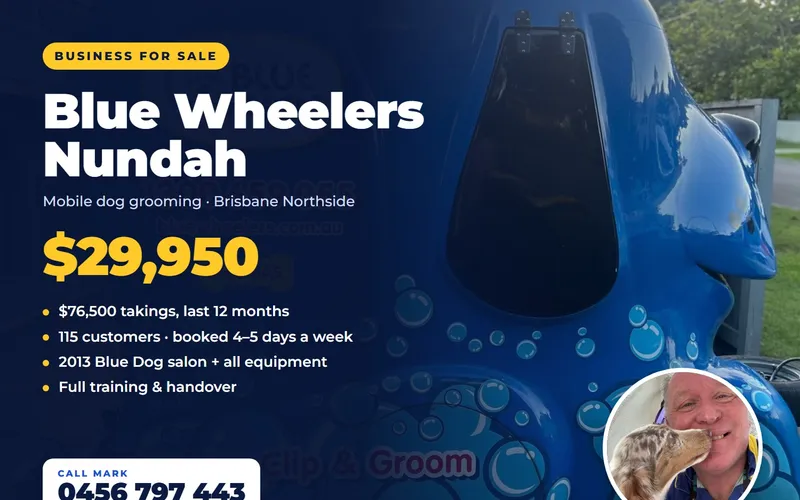
Established Blue Wheelers Mobile Dog Grooming Business – Nundah, Brisbane Northside
Established Blue Wheelers mobile dog grooming business on Brisbane's northside: 115 customers, about $76,500 in takings over the last 12 months, booked 4–5 days a week, with full training and handover.
Local tradies on TradiHub AI
See all →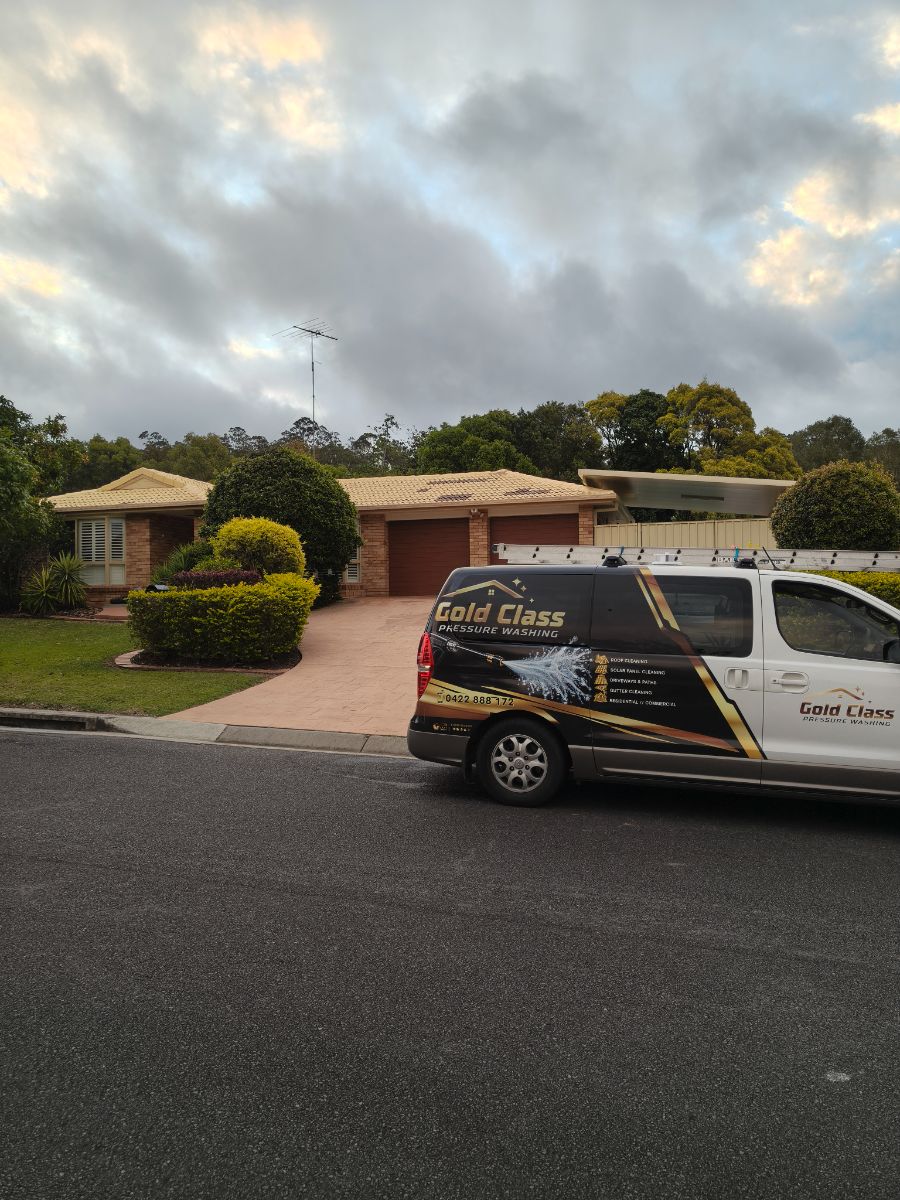
Gold Class Pressure Washing
Cleaning · Pressure Cleaning
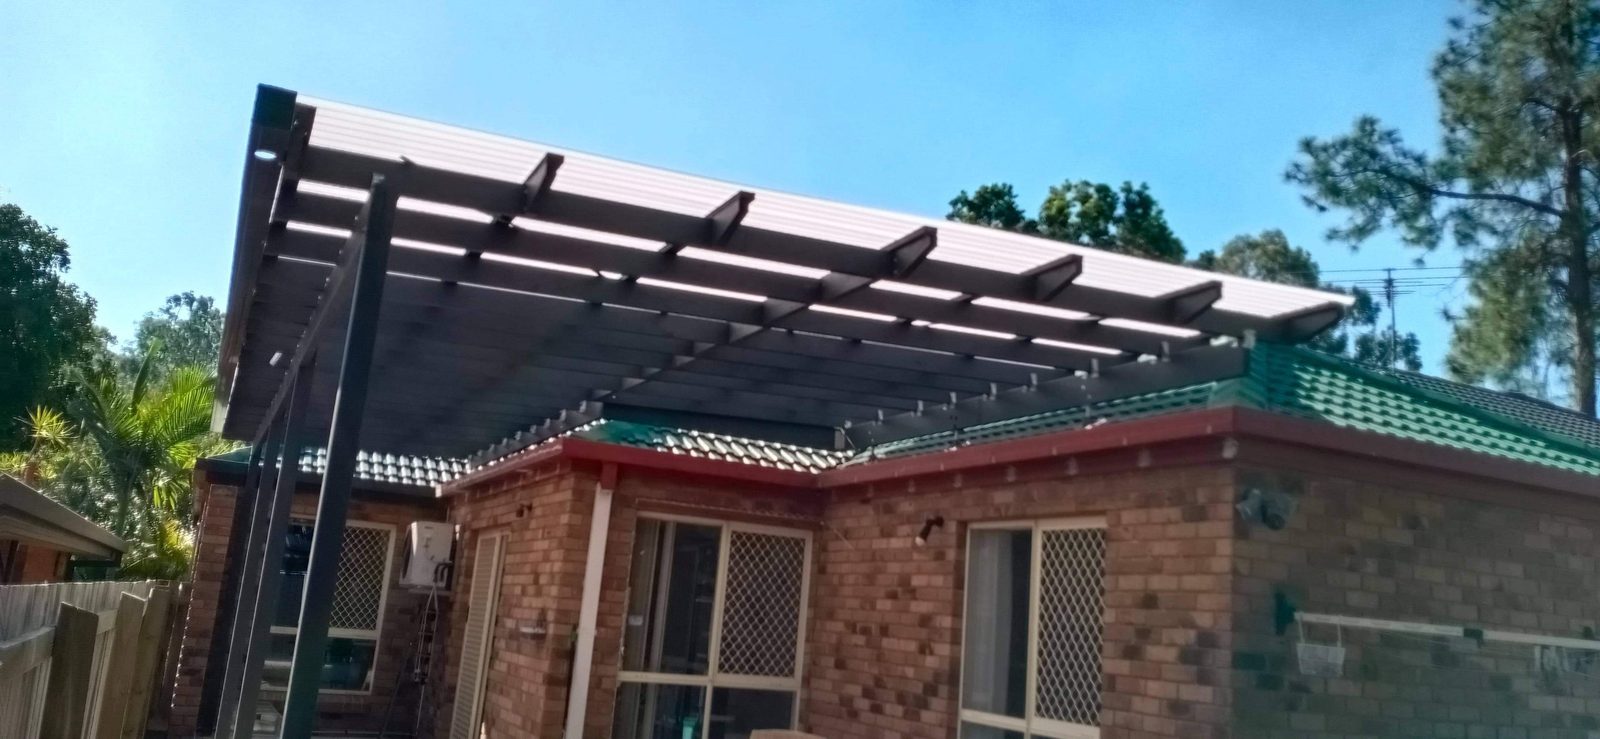
Masteredge Carpentry & Maintenance
Carpentry · Handyman · Decking & Pergolas
ZC Property Maintenance
Painting · Carpentry · Cleaning
Find local:Carpenters in Brisbane CBDCarpenters in ChermsideCarpenters in NundahCarpenters in Carindale
For tradies
Tradies: get found by local homeowners
A free-to-start local directory with your real Google reviews and an ABN-checked tick. No per-lead fees, no lock-in. Founding members wanted.