First Home Guarantee vs FHSS: Which Scheme Saves You More?
Australia's two flagship first-home buyer schemes work very differently — here's how to compare them side by side and decide which one to use first.

Navigating government help as a first home buyer in Australia can feel like reading two different instruction manuals for the same destination. The First Home Guarantee (FHBG) and the First Home Super Saver (FHSS) scheme are both genuinely useful — but they solve different problems, have different eligibility rules, and can't always be used interchangeably. Here's a plain-English comparison so you can figure out which one actually helps your situation.
What Each Scheme Actually Does
First Home Guarantee (FHBG) The FHBG lets eligible buyers purchase a home with as little as a 5% deposit without paying Lenders Mortgage Insurance (LMI). The federal government guarantees up to 15% of the loan to your lender, bridging the gap to 20%. In 2026, 35,000 places are available per financial year across the scheme and its related streams (Regional First Home Buyer Guarantee and Family Home Guarantee).
First Home Super Saver (FHSS) The FHSS lets you make voluntary contributions into your superannuation fund and later withdraw them — along with associated earnings — to use as a home deposit. You can release up to $50,000 of eligible contributions. Because super contributions are taxed at 15% rather than your marginal rate, the savings can be meaningful if you're a mid-to-high income earner.
Side-by-Side Comparison
| Feature | First Home Guarantee | FHSS Scheme |
|---|---|---|
| What it helps with | LMI cost (saves $10K–$35K+) | Building a deposit faster via tax savings |
| Minimum deposit needed | 5% of purchase price | No minimum — you build it over time |
| Income cap (2026) | $125,000 single / $200,000 couple | No cap |
| Property price cap | Varies by state/region | No cap (but withdrawal limit is $50,000) |
| Time to benefit | At purchase | Requires years of contributions first |
| Can you combine both? | Yes, in most cases | Yes, in most cases |
Who Benefits Most From the FHBG
The guarantee is best suited to buyers who:
- Already have a 5% deposit saved and want to buy now rather than wait
- Are in a lower income bracket where the tax benefits of super contributions are modest
- Are buying in a city or region where property prices are close to or under the scheme's price caps
Ready to get started? Post your job free and local first home buyers tradies can quote.
The LMI saving is the headline benefit. On a $700,000 property with a 5% deposit, LMI could otherwise cost $20,000–$30,000 depending on the lender. The guarantee eliminates that cost entirely.
Check current property price caps at the Housing Australia website before assuming you qualify — Sydney and Melbourne caps are higher than regional caps, and they're reviewed periodically.
Who Benefits Most From the FHSS
The FHSS suits buyers who:
- Are still 2–5 years away from purchasing and have time to accumulate contributions
- Earn above $45,000 a year, where the 15% super tax rate beats their marginal rate
- Want to use both salary sacrifice and after-tax contributions to maximise the $50,000 ceiling
At a marginal rate of 32.5%, every $1,000 contributed via salary sacrifice saves roughly $175 in tax compared to saving the same amount from your take-home pay. Over four years of consistent contributions, that's a meaningful difference.
Be aware: the ATO must approve your FHSS release request before you sign a contract. There's no flexibility on that sequencing, and if you don't purchase within 12 months of release, the funds must go back into super or you face a tax penalty.
The Case for Using Both
These schemes are not mutually exclusive. A common strategy:
- Spend 2–4 years making voluntary super contributions under the FHSS
- Withdraw up to $50,000 to form part of your deposit
- Apply for the FHBG at purchase so you don't need to reach 20% and avoid LMI
This combination works particularly well for couples — each partner can access up to $50,000 from FHSS, potentially giving you $100,000 in deposit funds, while the FHBG handles the LMI gap.
Common Mistakes to Avoid
- Waiting too long to apply for FHBG places — they're allocated on a first-come, first-served basis each financial year and do run out
- Not checking FHSS eligibility early — you can only count contributions made after you first become eligible, so delaying costs you time
- Assuming any property qualifies — both schemes have conditions around property type (some exclude investment properties or owner-builder situations)
- Forgetting state-based grants — the FHOG (First Home Owner Grant) in your state may stack on top of federal schemes
Actionable Takeaway
If you're buying within the next six months, focus on the First Home Guarantee first — confirm your eligibility, check the price cap for your target area, and find a participating lender. If your purchase is still a few years away, start FHSS contributions now and revisit the guarantee closer to purchase. Talk to a mortgage broker and an accountant together: the tax angle of FHSS genuinely warrants both conversations.
Done researching? The next step is getting real quotes.
Get My Quotes — It’s Free →No obligation. Takes 60 seconds.
Business for sale
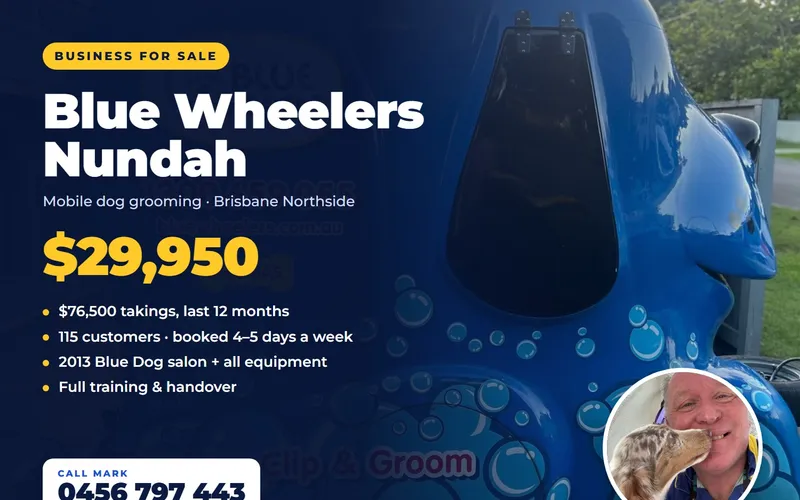
Established Blue Wheelers Mobile Dog Grooming Business – Nundah, Brisbane Northside
Established Blue Wheelers mobile dog grooming business on Brisbane's northside: 115 customers, about $76,500 in takings over the last 12 months, booked 4–5 days a week, with full training and handover.
Local tradies on TradiHub AI
See all →
Gold Class Pressure Washing
Cleaning · Pressure Cleaning
ZC Property Maintenance
Painting · Carpentry · Cleaning
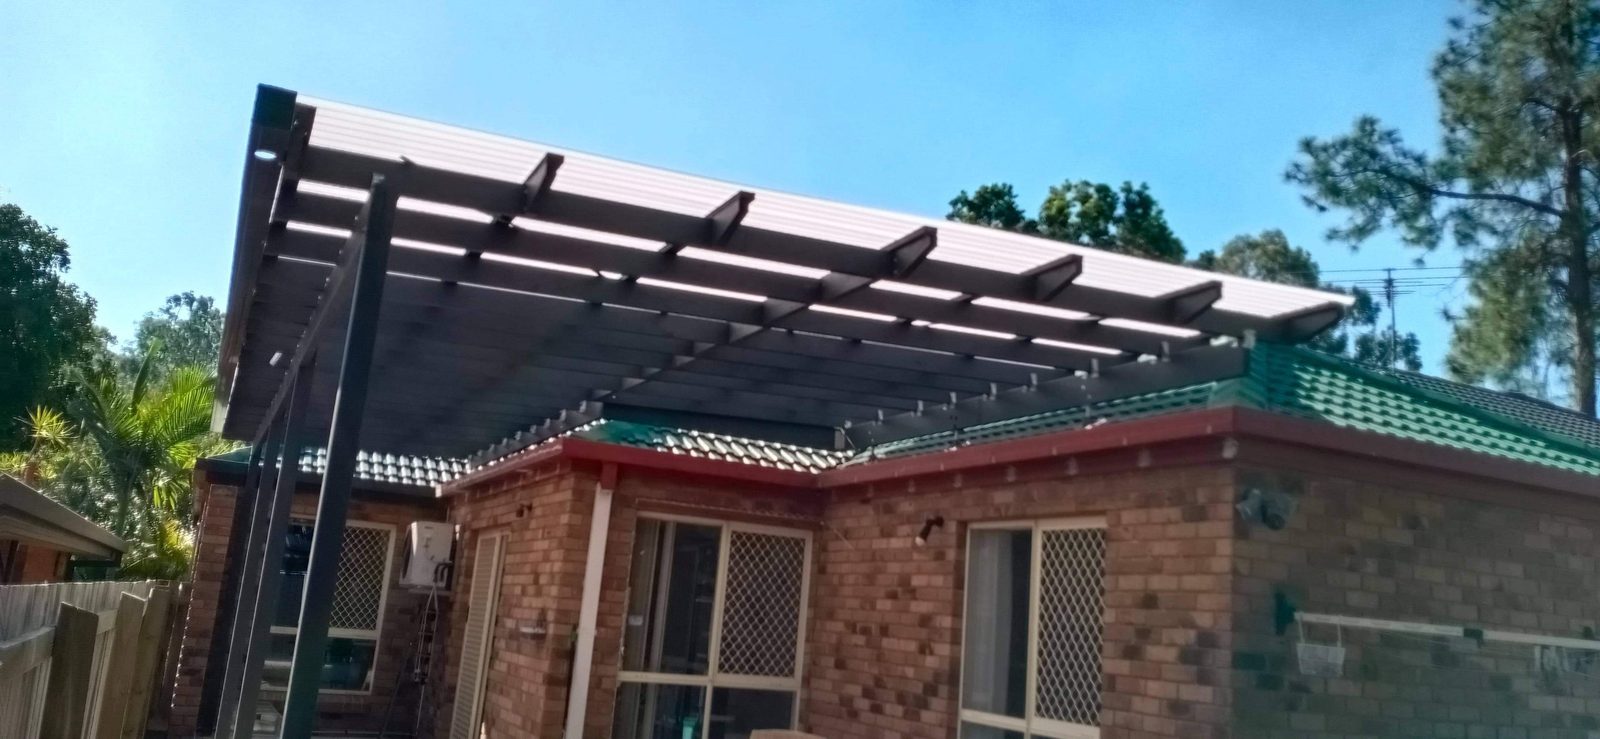
Masteredge Carpentry & Maintenance
Carpentry · Handyman · Decking & Pergolas
Find local:Carpenters in Acacia RidgeCarpenters in IndooroopillyCarpenters in ToowongCarpenters in Bulimba
For tradies
Tradies: get found by local homeowners
A free-to-start local directory with your real Google reviews and an ABN-checked tick. No per-lead fees, no lock-in. Founding members wanted.